
Planning a house demolition in Brisbane involves more than hiring a contractor and booking machinery. Before demolition begins, the right insurance must be in place to protect you, your neighbours, and everyone working on site.
Incorrect or missing insurance can expose property owners to serious financial risk and project delays. Whether you are preparing for a knockdown rebuild or clearing a residential site, knowing what cover is needed helps you avoid problems before work starts.
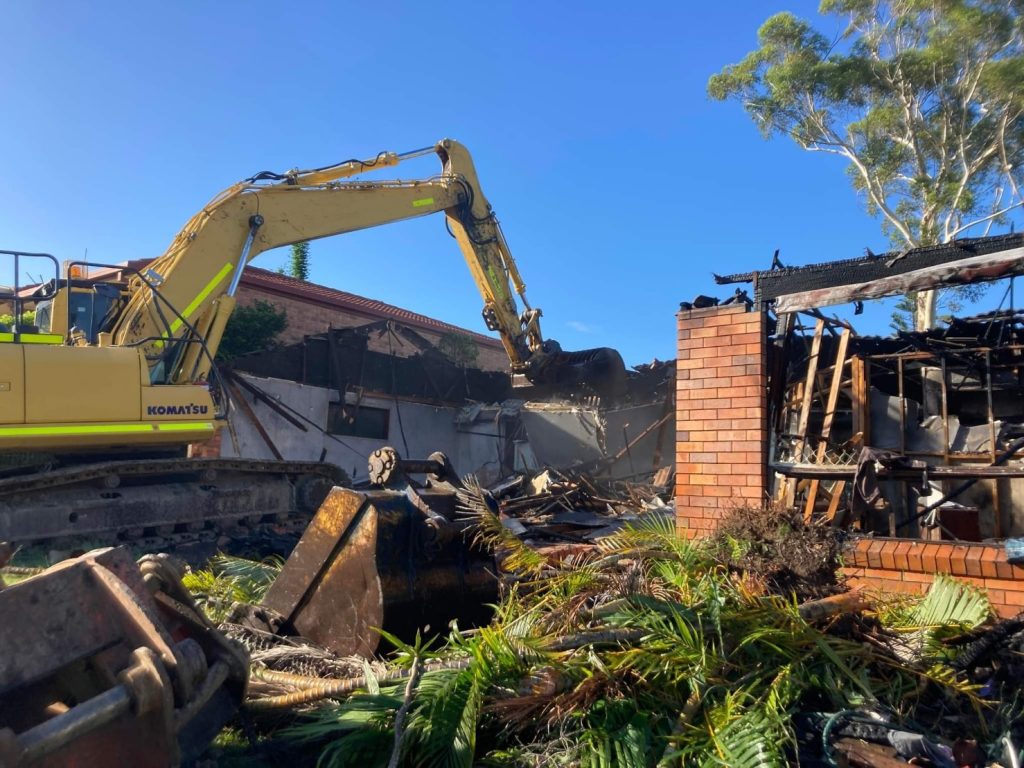
Public Liability Insurance for House Demolition in Brisbane
Public liability insurance is the most critical insurance cover for any house demolition in Brisbane. It protects against injury to third parties or damage to surrounding property caused by demolition activities.
Demolition carries inherent risks beyond the site boundary. Falling debris, dust, vibration from machinery, and accidental damage to neighbouring fences, driveways, or buildings can all result in claims.
Cover amounts vary between contractors. Ask your builder, insurer or certifier what level suits your project, and check the contractor’s cover meets it. Always request a current certificate of currency and confirm that demolition activities are specifically covered under the policy.
If you are undertaking a knockdown rebuild, do not assume your builder’s insurance automatically covers demolition. Some building policies only commence once construction begins. Always confirm in writing where responsibility for demolition insurance sits.
Workers Compensation Insurance
Under Queensland law, any demolition contractor employing workers must hold workers compensation insurance through WorkCover Queensland.
While property owners are not required to hold workers compensation themselves, you must ensure your demolition contractor has valid cover. If a contractor does not carry workers compensation and a worker is injured on your site, liability may fall back on you.
Before work begins, request confirmation that workers compensation is current and covers all workers attending your Brisbane property, including subcontractors and labour-hire personnel. Reputable demolition companies provide this information without hesitation.
Property Insurance During Demolition
Many standard home and contents policies exclude or limit cover during demolition, so check yours before work starts.
If your property still has structures on site during demolition, or if demolition is staged, you should speak with your insurer before work begins. Some insurers can offer temporary cover during the demolition period, while others require a separate policy.
For knockdown rebuilds, insurance gaps during demolition are common and often overlooked. Without appropriate cover, damage caused by storms, vandalism, or fire during demolition may not be insured.
Contract Works Insurance
Contract works insurance covers damage to the structure being demolished and associated works during the demolition process. This is commonly held by professional demolition contractors and is particularly relevant for complex demolitions, partial demolitions, and sites near neighbouring structures.
You should confirm whether your contractor holds contract works insurance and what activities are covered.

Asbestos Removal Insurance
Many Brisbane houses built before 1990 contain asbestos. Where asbestos is present, removal must be carried out by appropriately licensed professionals with specific insurance coverage.
Many Brisbane houses built before 1990 contain asbestos. Where asbestos is present, it must be removed by appropriately licensed professionals. Ask them to show their licence and insurance, including cover for asbestos-related risks such as contamination and exposure claims. This matters most where neighbouring properties may be affected.
Queensland rules expect asbestos to be identified before demolition begins, so a pre-demolition inspection is standard for older homes. Under sections 452 and 453 of the Work Health and Safety Regulation 2011, asbestos likely to be disturbed by demolition must be removed first, as far as is reasonably practicable. See how asbestos is identified before demolition and our asbestos removal service.
Never engage a contractor who offers to handle asbestos without licensed removal and documented insurance. Improper removal can expose property owners to cleanup costs, regulatory penalties and long-term liability.
Professional Indemnity Insurance
Professional indemnity insurance applies where professional advice or design input is involved. This may include structural engineers, demolition planning consultants, or project managers.
For standard house demolition, professional indemnity insurance is usually held by engineers or consultants engaged for reports or approvals rather than by the demolition contractor themselves.
If engineering advice is required to assess neighbouring structures or site stability, ensure those professionals carry appropriate professional indemnity cover.
Environmental Liability Considerations
While less common in residential demolition, environmental risks can still arise. These include contaminated soil, buried materials, or historic site usage that creates pollution issues during demolition.
Professional demolition contractors manage these risks through compliant procedures. In higher-risk sites, additional environmental liability cover may be required. This is more common in commercial or former industrial properties than standard Brisbane house demolitions.

What Happens If Insurance Is Inadequate
Proceeding with house demolition in Brisbane without proper insurance exposes property owners to serious financial and legal consequences.
If damage occurs to neighbouring property or a person is injured, you may be personally liable for compensation, legal costs and remediation works. Work can also be stopped if approvals or safety requirements are not met. See which approvals apply in Brisbane.
Insurance is a standard part of professional demolition in Brisbane, and a gap can be expensive.
How to Check Your Demolition Contractor’s Insurance
Before you engage a demolition contractor, ask for:
- A current certificate of currency for public liability insurance
- Policy dates that cover your whole demolition period
- Confirmation that demolition work is not excluded
- Confirmation that the cover amount suits your project
- Proof that workers compensation is active, including for subcontractors
For larger projects, your solicitor or insurance broker can review the documents for gaps. Our guides cover questions to ask before hiring a demolition contractor and how to compare quotes from demolition companies in Brisbane.
Owner-Builder Demolition Insurance
If you plan to demolish as an owner-builder, you take on responsibility for insurance and safety yourself. You may need public liability insurance, workers compensation if you engage workers, and contract works insurance. Talk to your insurer first, and check licensing requirements with Workplace Health and Safety Queensland. For most Brisbane homeowners, a professional demolition company is the simpler and safer option.
House Demolition in Brisbane Done Properly
Insurance is a standard part of safe, compliant house demolition in Brisbane. The right cover protects you, helps prevent delays and lets your project go ahead without problems.
Next Gen Demolition is licensed and insured for demolition and asbestos removal. Contact us for a free quote on your house demolition in Brisbane.